Keep more of what you build. Protect the people who helped you build it.
JSW Innovative Solutions helps Arizona business owners and their families keep more of what they earn. Junell Stepanek explains defined benefit plans, retirement strategy and estate planning in plain English, works alongside your CPA, and only brings strategies she would stand behind. It starts with a conversation, with no obligation.
What can we help you with?
Four things. Defined benefit and cash balance plans for owners who are already maxing a 401(k). Retirement and legacy planning for families within about ten years of retirement. Solo 401(k) plans for the self-employed. And employee benefits for employers with W-2 teams. Every option is explained plainly and reviewed with your CPA first.
- 01Defined benefit and cash balance plansFor owners who already max a 401(k) and still write a large check every April. A pension you set up for yourself, with contributions an actuary calculates each year and your business deducts.
- 02Retirement and legacy planningFor families within about ten years of retirement. Pull scattered accounts together, decide Roth versus traditional on purpose, build an income plan you understand, and get your estate documents in order.
- 03Solo 401(k) plans for the self-employedFor business owners and independent professionals with no full-time employees other than a spouse. Contribute as both employee and employer, choose Roth or traditional, and keep the plan simple to run.
- 04Employee benefitsEmployee benefits for Arizona employers with W-2 teams, from Dahl Stepanek Benefits Group, an independent team that works with several providers and starts with your people.
How does working with us actually go?
It starts with a conversation about your goals, income and what you already have in place. If a strategy fits, you get it in writing with every assumption spelled out, and we review it with your CPA before you decide. After that we handle the paperwork, the plan administrators and the annual check-ins.
A plain-English conversation
We learn your goals, your business and what you are already doing. No pitch. If something will not fit, you hear that first.
A plan your CPA can review
You get the strategy in writing with the assumptions spelled out. We walk your CPA through it before you decide anything.
We carry the follow-through
Paperwork, plan administrators, rollovers and annual check-ins. You approve the decisions; we handle the rest.
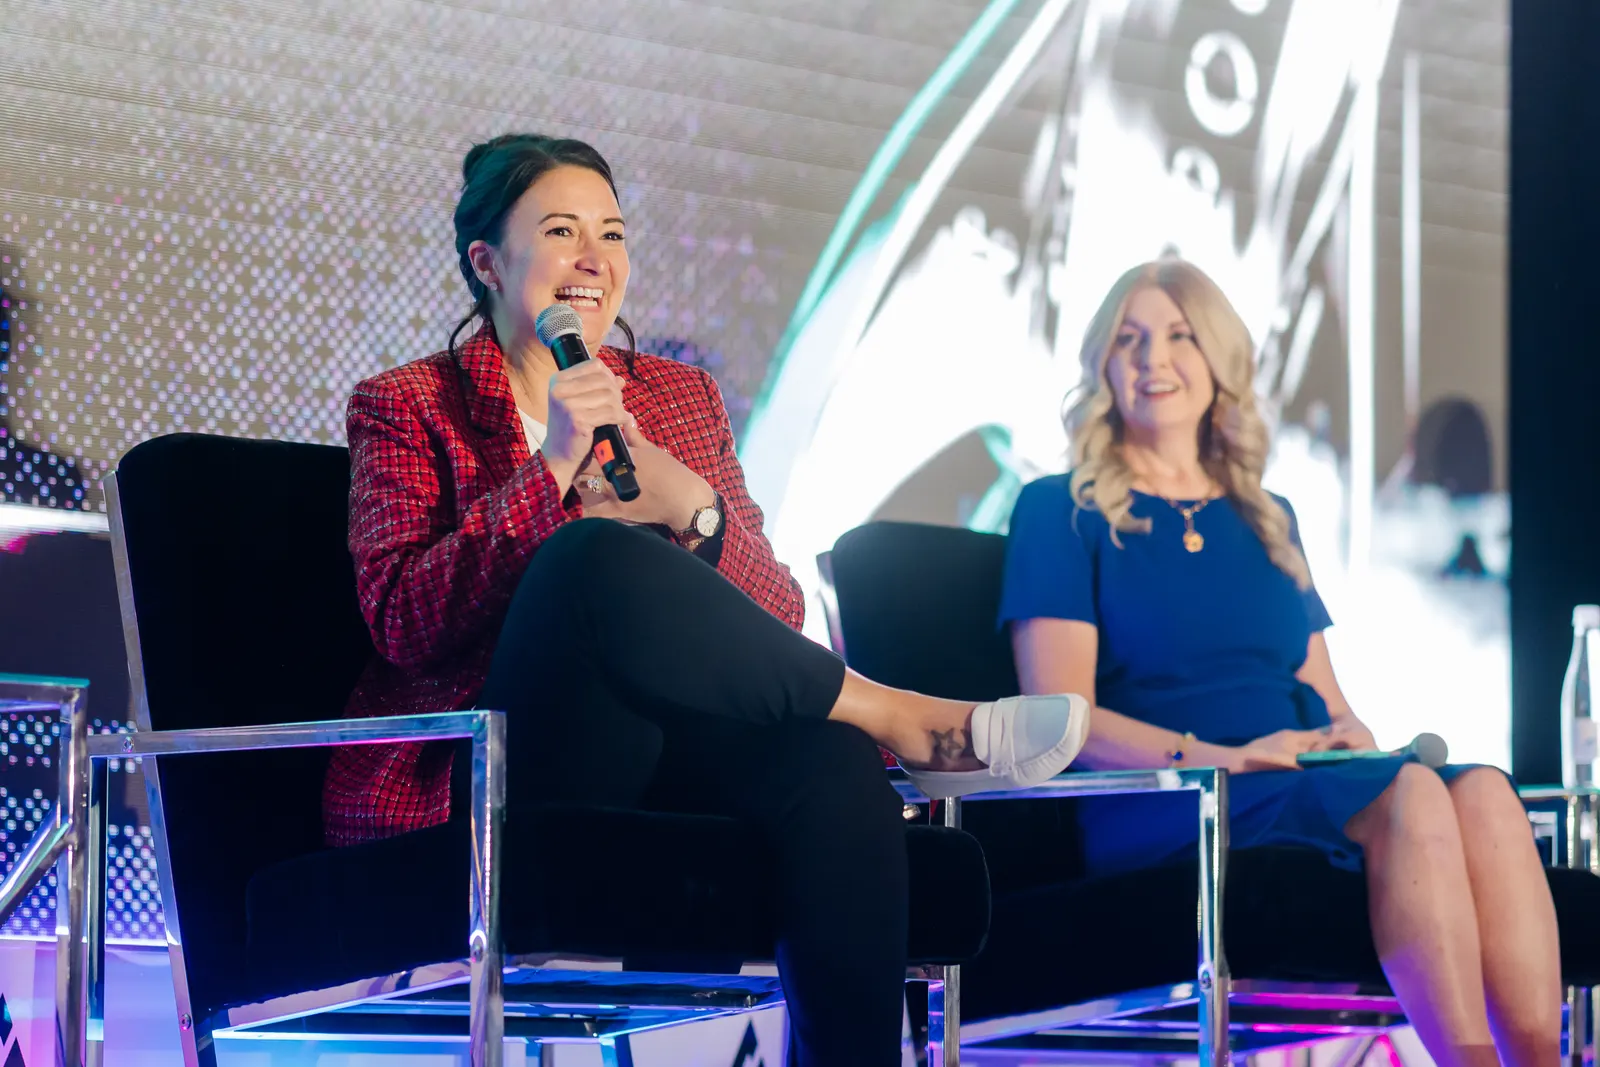
A strategist who teaches first and sells never.
Junell Stepanek leads JSW Innovative Solutions, built to give business owners and families what she kept seeing them go without: someone who explains the rules in plain English, works with their CPA instead of around them, and is honest about what fits and what does not.
Is a defined benefit plan a loophole?
No. A defined benefit plan is a pension, one of the oldest retirement structures in the tax code. Owners set one up for themselves, an actuary calculates the allowed contribution each year, and the business deducts it. It suits steady, high-income owners who are already maxing a 401(k). Your CPA should confirm fit and deductibility.
Do you work with my CPA or around them?
With them, every time. Any strategy we recommend goes to your CPA with the assumptions spelled out, and we are happy to meet together. Your CPA knows your full tax picture, and the best plans happen when the advisor, the CPA and you are looking at the same numbers.
What does it cost to work with you?
The first conversation costs nothing and carries no obligation. If a plan makes sense, every setup and annual fee is put in writing before you sign, including what the plan administrator or custodian charges. There are no surprises after the fact, and you can ask about any line item.
When should I start year-end planning?
Now, if you are an owner with a large tax bill. A new defined benefit plan generally has to be adopted by the business tax filing deadline, including extensions, to count for that year, and setup takes several weeks. Fall is when owners sit down with their CPAs, so it is the right time to look.
Where do you work?
We are based in Gilbert and work with business owners and families across Arizona, including Gilbert, Phoenix, Scottsdale and Tempe. Meetings happen in person or by video, whichever is easier for you and your CPA. If you are elsewhere in the state, reach out and ask.
In their words
From the beginning, Junell was very friendly while maintaining her professionalism. I trusted her with all the numbers, and she did all the contacting with the company, bringing me in on Zoom calls when necessary. She made it so easy for me to understand everything, and she made me feel like a friend, listening to what I needed and helping me achieve it. I would highly recommend her.
I thought Junell was going to try to sell me life insurance to cover my HELOC balance, but she never did. She had a better idea based on my own situation. I had never heard of a Solo 401(k), and she took her time to explain everything. It took a while to convince me, but the end result was well worth it.
What do business owners ask us first?
Usually some version of: is this legitimate, what does it cost to run, and what will my CPA think. The short answers: these are long-standing structures in the tax code, we tell you the ongoing costs up front, and we bring your CPA into the conversation before you decide anything.
Who does JSW Innovative Solutions work with?
Arizona business owners and their families. That includes owners of professional practices and closely held businesses, self-employed professionals, and families within about ten years of retirement. Most clients already work with a CPA, and we bring that CPA into every tax strategy before a decision is made.
What is a defined benefit plan?
A defined benefit plan is a pension. An owner sets one up through the business, an actuary calculates the allowed contribution each year based on age, pay and the retirement benefit being funded, and the business deducts the contribution. For established, high-income owners it can allow far larger contributions than a 401(k).
What is the difference between a defined benefit plan and a cash balance plan?
A cash balance plan is a type of defined benefit plan. Instead of expressing the benefit only as a future monthly pension, it shows each participant a hypothetical account balance that grows with contributions and a stated interest credit. Many owners find it easier to understand, and the funding rules are similar.
How do I know if a defined benefit plan fits my business?
It usually fits owners who are roughly 45 to 65, earn a steady income of about $250K or more, already max a 401(k), have three or more years of consistent profit and a small or younger team. It usually does not fit owners with volatile income or who need the cash soon.
What does a defined benefit plan cost to run?
A third-party administrator and actuary design the plan and run the annual calculations. Annual fees are typically a few thousand dollars, and you see them in writing before you sign. Eligible employees are covered under the plan's rules, and the administrator models that cost up front.
Start with a conversation.
Tell us what you are working on. We will tell you plainly what fits, what does not, and what to ask your CPA.